

Ether.fi Cash Card Review 2026
Reviewed by Mihail B. in · · how we verify
Algorithmic score, not user reviews: how it is calculated
Partner link. We may earn a commission, which never affects the rating or where this card ranks.
Fees and limits
| Issuance fee | First virtual card free (Core 1, Luxe 4, Pinnacle 10, VIP 50), except that Core members in Argentina, Angola…The fine print
|
|---|---|
| Annual fee | Free; Luxe and Pinnacle can be bought outright at $199/year and $999/year instead of earning them with points |
| FX fee | 0% on USD purchasesThe fine print
|
| ATM limit | Up to $5,000 per withdrawal, 5 withdrawal attempts and $25,000 per rolling 24 hours, the same on every tier and both…The fine print
|
| Spending limit | Self-set in-appThe fine print
|
Fees change; the current ones are in Ether.fi Cash’s terms.
Features
- Cashback: Up to 3%
The fine print
- … cashback on Core, Luxe and Pinnacle (4% on VIP), paid in ETHFI since September 2026: a help article says every qualifying transaction "earns cashback in ETHFI. This will display in your assets list as ETHFI", converted at the ETHFI price when the purchase clears, then locked for 7 days
- A minimum of $5 in cashback is needed to claim
- Before this change cashback landed as USDC (our July 2026 purchase paid back USDC)
- Monthly ladders: Core 3% to $2,000, 1% to $3,000, 0.5% above
- Luxe 3% to $10,000, 1% to $20,000, 0.5% above
- Pinnacle 3% to $50,000, 1% to $80,000, 0.5% above
- VIP 4% to $50,000
- Euro purchases earn on a shorter ladder measured in USD equivalent: Core 3% to $800, 1% to $1,500, 0.1% above (Luxe $3,000/$6,000, Pinnacle $16,000/$26,000), and USD and EUR share one monthly counter
- Luxe and above add category cashback on named subscriptions (10% up to $10 a month on Luxe, 20%/$20 Pinnacle, 30%/$30 VIP)
- Pinnacle and VIP add 25% on airport fast-track fees, up to $25 a year on Pinnacle and $50 on VIP
- Tiers are earned monthly with points, by staking 30,000 ETHFI for Luxe or 150,000 for Pinnacle, by a Liquid deposit of $15K/$100K, or by paying $199/$999 a year
- Points earn at 1.5 per $1k staked per day, 10 per $1k in Liquid per day, 1,000 per $1k of card spend and 5 per 1K ETHFI staked per day
- KYC: Yes
- Card type: Virtual + Physical
- Top up with: USDC, USDT, EURC, frxUSD, eUSD, wETH, weETH, eBTC, ETHFI, sETHFI, wHYPE, SCR, LiquidETH, LiquidBTC, LiquidUSD…
Full list
… LiquidReserve via Ethereum, Base, Arbitrum, Scroll, Solana, Tron (Direct Pay: USDC, LiquidUSD only; Solana USDC and Tron USDT: no-fee 1:1 transfer)
- Available countries: United States, Canada, Mexico, Brazil, Argentina, Chile, Colombia, Costa Rica, Dominica, Dominican Republic, Ecuador…
Full list
… El Salvador, Guatemala, Guyana, Honduras, Panama, Paraguay, Peru, Uruguay, Antigua and Barbuda, Bahamas, Barbados, Belize, Bolivia, Saint Kitts and Nevis, Saint Lucia, Saint Vincent and the Grenadines, Suriname, Trinidad and Tobago, Puerto Rico, United Kingdom, France, Germany, Italy, Portugal, Spain, Belgium, Austria, Switzerland, Poland, Czech Republic, Denmark, Croatia, Cyprus, Greece, Ireland, Luxembourg, Romania, Slovakia, Slovenia, Sweden, Bulgaria, Latvia, Andorra, Iceland, Malta, Lithuania, Gibraltar, Hong Kong, Japan, Thailand, South Korea, Taiwan, Singapore, Indonesia, Malaysia, Philippines, Bangladesh, Australia, New Zealand, Saudi Arabia, United Arab Emirates, Bahrain, South Africa, Angola, Hungary, Norway, Liechtenstein, Monaco, Guernsey, Jersey, Isle of Man, Cayman Islands, British Virgin Islands, Turks and Caicos Islands, Maldives, Palau, Vanuatu, Oman, Seychelles, Nigeria
Who issues the Ether.fi Cash Card
The Ether.fi Cash Card is issued by Third National (Nimbus LLC), USA; Puerto Rico money transmitter (NMLS #2612780), a subsidiary of Signify Holdings, Inc. ("Rain") per Rain's privacy policy. The issuer is named in the source linked below.
Primary source · All cards issued by Third National (Nimbus LLC) · Why the issuer matters
Supported cryptocurrencies
You can load the Ether.fi Cash Card with crypto; the 5 assets we track for it are listed below.
Pros and cons
Pros
- True non-custodial credit card
The fine print
- Borrow against DeFi collateral
- Earn yield while spending
- Cashback in ETHFI with a 7-day lock
- Visa Signature benefits ($10k protection)
- Physical cards: plastic (Core), purple metal (Luxe), black metal (Pinnacle), gold metal (VIP)
- No-fee funding via Solana USDC and Tron USDT
- No annual maintenance fee
- Banking rails: SEPA / SWIFT support
Cons
- Requires crypto collateral
The fine print
- The borrow rate is variable, set by Aave v4 markets, not fixed
- Not available in the Netherlands, Finland or Estonia, nor in twenty US states
- Core members in fourteen regional-pricing countries pay $10 for the first virtual card
- Cashback is paid in ETHFI and locked 7 days, so its dollar value moves with the token
- Rates decrease after monthly spend caps
- Some merchants declined under high-risk category rules (age-restricted alcohol and tobacco shops reproduced across several merchants in several European countries)
Regional availability
Available in 91 countries
91 countries and territories: 88 with virtual and physical cards, Belgium and Ireland with virtual cards only, and the United States. Most of Europe including Hungary, Norway, Liechtenstein and Monaco, except the Netherlands, Finland and Estonia; the UK, Guernsey, Jersey and the Isle of Man; the Americas and much of the Caribbean; UAE, Saudi Arabia, Bahrain, Oman, Hong Kong, Japan, South Korea, Taiwan, Singapore and selected Asia-Pacific; South Africa, Angola and Nigeria. United States: thirty states plus the District of Columbia; not available in Arizona, Delaware, Georgia, Idaho, Louisiana, Maryland, Mississippi, Missouri, Montana, Nevada, New Mexico, North Dakota, Ohio, Oregon, Rhode Island, South Dakota, Tennessee, Vermont, Washington or Wisconsin. Not available in India, Israel, Turkey, Ukraine, Vietnam, China, Russia or any other jurisdiction the list omits.
Banking and fiat rails
The fine print
- … outgoing SEPA €0.90 plus any FX conversion, SEPA Instant deposits where the sending bank supports it
- No universal ether.fi minimum and no tier-based transfer limits, provider limits shown before confirmation
- IBAN: the SEPA article shows deposit details for an account "created for you with our third party provider" but does not call it a personal IBAN
- SWIFT: Yes for non-US residents, "generate your personal virtual bank account" with an account number and SWIFT code, $20 plus 0.1% per transfer
- US ACH $0.50 plus 0.1% and FedWire $20 plus 0.1% via virtual USD account details
- UK Faster Payments: unique sort code and account number, deposits only, £0.90 plus 0.20%
- Every inbound fiat transfer lands as a stablecoin
Card overview
Collateral stays on-chain while you spend. The first major credit card we've used where that's true, and we hold this one. The 3% rate is real: a $5.00 charge paid back exactly $0.15 in July 2026, and it arrived as USDC. Since 12 September 2026 the help centre says cashback "earns in ETHFI", converted at the token price when the purchase clears, locked for seven days, and claimable only once $5 has built up, so the dollar value of a month's rewards now moves with ETHFI between the purchase and the claim.
What the headline also hides is the ladder underneath it. Core pays 3% on the first $2,000 of monthly spend, 1% to $3,000, then 0.5% above that, so heavy months blend down fast. Luxe and Pinnacle push the 3% band out to $10,000 and $50,000, but the tier is not yours to keep: points reset every calendar month and Luxe wants 5,000 points again (it was 10,000 when we ran it in July), unless you stake 30,000 ETHFI, park $15,000 in Liquid, or pay $199 a year for it outright.
Euro purchases carry 0% FX, a benefit ether.fi only put in writing at the end of June 2026 and still ships with a beta label attached, paid for by a shorter cashback ladder that tapers after the first $800 of euro spend. Everything outside dollars and euros runs about 1%, and Core adds up to half a point on top of that.
In Direct Pay the money keeps earning until the moment it is spent; Borrow Mode instead draws credit against collateral at a variable rate the issuer does not print, described in one article as Aave v4 markets and in another as ether.fi's own lending market, and that interest is real too. The card also declines age-restricted merchants: we had alcohol and tobacco shops refused across several European countries, same category every time.
Available in the 91 jurisdictions on the issuer's list, all of which we list individually, with Belgium and Ireland on virtual cards only; the Netherlands, Finland, Estonia and 20 US states are excluded.
- Best fit
- DeFi-native spenders who already hold productive collateral, would rather borrow against it than sell it, and are happy to be paid in ETHFI
Common questions about the Ether.fi Cash Card
We do not collect user reviews. Answers come from the card terms, the issuer disclosure and the regulator registers we could reach, rechecked on the Data verified date above.
What are the fees for the Ether.fi Cash Card?
Is the Ether.fi Cash Card legit, and who is behind it?
Is the Ether.fi Cash Card worth it?
How does the Ether.fi Cash Card cashback work?
Where is the Ether.fi Cash Card available?
What cryptocurrencies does the Ether.fi Cash Card support?
Similar cards


Browse by category
Compare Ether.fi Cash Card
What that looked like
Straight from the account we opened. Card numbers, on-chain hashes and transaction IDs are redacted; nothing else is edited.
3% is exactly 3%
A $5.00 charge paid back $0.15, settled to the cent. Every purchase also carries an on-chain spend transaction, which we redacted here because it resolves to the wallet.

Captured 27 July 2026
The zero-FX claim on euros survives a real purchase
A EUR 138.00 charge settled at USD 158.882436, an effective rate of 1.151322. The ECB reference for that day was 1.1515, so the card came in 0.015% below it. It is also below Visa’s own published rate for the day, 1.155899. A euro purchase on Tria came to about 2% above the same benchmark.

Captured 4 August 2026
Euro spend still paid the top rate at this size
The same charge paid back EUR 4.14, which is 3.00% to the cent. Euro purchases run on a tighter cashback ladder than dollars, but it only starts tapering above EUR 800, and this purchase sat well under that. So the 0% FX benefit cost nothing here. It would above the threshold.

Captured 4 August 2026
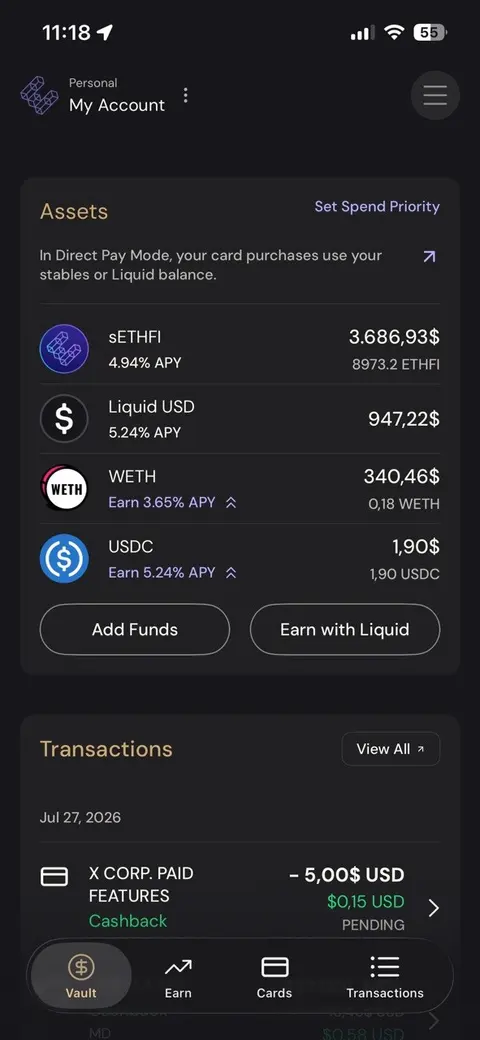
The balance keeps earning while you spend it
Direct Pay deducts purchases from stables or the Liquid position. Both were still paying yield at the time of the screenshot: sETHFI 4.94%, LiquidUSD 5.24%, WETH 3.65%.
Captured 28 July 2026
Alcohol and tobacco shops get refused
The decline mail blames a high-risk merchant category and links the issuer’s own help article. Same result at several shops, in different European countries, so it is the category and not one badly coded merchant.

Captured 31 March 2026
Flagged wrongly, cleared in under a day
Card services gone, bank transfers and Pix with them, on a suspicion of cashback farming that was not happening. Support checked and put the account back inside 24 hours. Funds stayed withdrawable on-chain the whole time.

Captured 7 May 2026
The 3% tier has to be re-earned every month
In July Luxe wanted 10,000 points per calendar month, with three days left on the clock here, or 15K staked ETHFI to skip the counter. Since September the help centre asks for 5,000 points or 30K ETHFI.

Captured 28 July 2026
Half the tier came from holding, not spending
Card spend contributed 5,707 points that month; sETHFI and LiquidUSD added 5,159 between them. sETHFI is counted in tokens rather than dollars, so its rate survives a price drop.

Captured 28 July 2026